Winners, Losers, and the ROI Reality of Eurasian Print Technology in the American Market
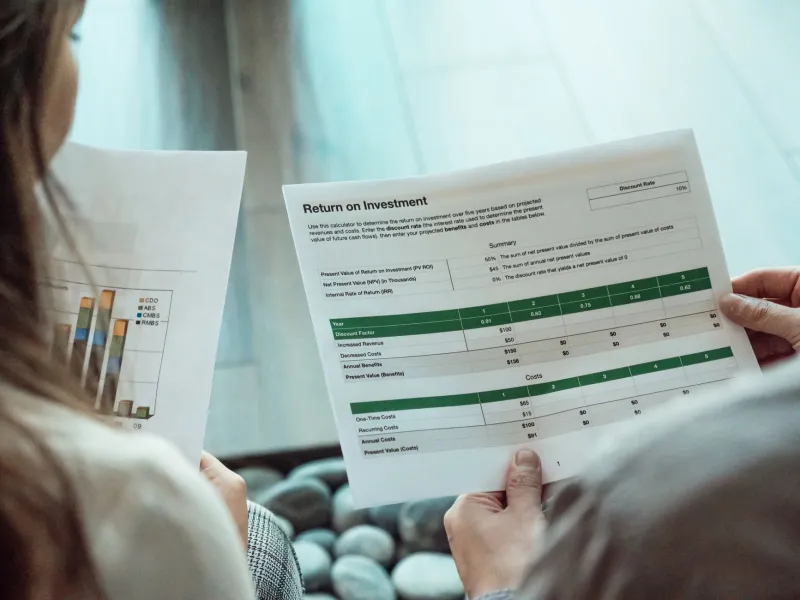
Capital investment conversations in the US print industry have a particular texture. They are equal parts aspiration and anxiety — the aspiration of expanded capability, faster throughput, and new market access, set against the anxiety of debt service, integration cost, and the nagging question of whether the technology will actually perform in this shop, for these customers, at this margin.
For the segment of American print operations that have turned to European and Asian equipment and technology to answer those aspirations, the outcomes have been far from uniform. Some verticals have generated returns that justify the investment with room to spare. Others have absorbed the cost of Eurasian technology bets without capturing the revenue growth that was supposed to follow. Understanding the difference is less about which equipment is objectively better and more about the structural fit between a specific technology and a specific business model.
The Verticals That Have Genuinely Won
Labels and Packaging
Among US print verticals, label and flexible packaging producers have shown the most consistent ability to generate strong ROI from European-sourced narrow-web and mid-web press technology. The economics are favorable for a specific reason: the customer base in this segment — food and beverage brands, specialty consumer goods manufacturers, pharmaceutical companies — has demonstrated consistent willingness to pay for quality differentiation and short-run flexibility.
European press manufacturers, particularly those from Germany and the Netherlands, have long led in narrow-web UV inkjet and combination printing platforms. US label converters who invested in these platforms during the past four to six years have generally reported payback periods in the three-to-five-year range, with margin improvement driven by the ability to capture premium short-run work that offset-only operations cannot profitably produce.
A label converter operating in the upper Midwest with revenues in the $8–12 million range provides a representative example. Following the acquisition of a European combination press platform, the operation shifted approximately 30 percent of its revenue mix toward shorter runs at higher per-unit margins. Equipment debt service was covered within the projected window, and the shop has since added a second unit.
Soft Signage and Interior Décor Textiles
The domestic soft signage and interior textile printing market has been another consistent bright spot for Eurasian technology investment. European dye-sublimation and direct-to-fabric platforms have enabled US operations to compete in retail display, trade show graphics, and architectural textile applications that were previously dominated by offshore production.
The margin structure in this segment supports the investment. Soft signage commands price premiums over conventional banner and display materials, turnaround expectations from retail and event clients frequently preclude offshore sourcing, and the visual quality requirements are high enough to reward equipment capability. Shops that positioned themselves correctly in this space — with European printing platforms, finishing equipment, and fabric sourcing relationships — have built defensible business models.
The Verticals Where the Math Has Been Harder
Commercial Offset and General Wide-Format
US commercial print operations that pursued European press technology in the conventional offset category have faced a more complicated return calculation. The equipment itself — representing the best of German and Japanese engineering — is often technically superior to what it replaced. The problem is market context.
Commercial print pricing in the US has remained under sustained pressure from overcapacity and digital substitution. Investing in a technically superior press does not, by itself, create pricing power in a commodity-driven market. Shops that bought European offset capacity expecting volume-driven ROI have frequently found that the volume didn't materialize at the margins the investment required.
General wide-format production has shown similar dynamics. Asian-manufactured wide-format equipment at competitive price points has effectively commoditized the entry and mid-market segments. US shops that invested in premium European wide-format platforms to compete in those segments have struggled to extract pricing that justifies the cost differential. The premium European platforms do win in high-end applications — fine art reproduction, architectural visualization, premium retail display — but those niches require sales and marketing capabilities that many print shops have not developed.
Volume Promotional Products
US promotional products operations that pursued Asian manufacturing technology — specifically high-speed pad printing, automated garment decoration, and large-format UV flatbed systems — to compete on volume have had mixed results. The technology performs. The competitive environment it places operators into is brutal.
Asian suppliers of promotional goods have continued to invest in automation and scale at a pace that domestic operations cannot match on a cost-per-unit basis. US shops that attempted to win on volume using Asian-sourced technology found themselves in a cost competition with suppliers whose structural cost advantages extend well beyond equipment.
The operations that have done well in this space are those that used Asian technology not to compete on volume but to enable customization, speed-to-market, and minimum order flexibility that offshore suppliers cannot match. The technology is a means to a differentiated market position, not a path to cost parity.
A Framework for Evaluating the Next Investment
The pattern across these verticals suggests a framework that US print buyers can apply before committing to Eurasian technology investments.
Does your customer base reward quality differentiation? If yes, premium European technology platforms are more likely to generate ROI. If your market competes primarily on price, the math is harder regardless of equipment origin.
Can the technology enable a market position your current equipment cannot? The strongest ROI cases involve technology that opens genuinely new revenue streams — new substrates, new applications, new customer segments — rather than technology that does the same work faster. Incremental efficiency gains rarely justify the capital cost and integration burden.
What is the realistic implementation timeline to full productivity? Most shops underestimate this by a factor of two. A realistic payback calculation should use a production ramp that reflects actual operator training timelines and workflow integration complexity, not vendor-projected timelines.
What does the support infrastructure look like in your region? This question matters more than most buyers ask it. A technically excellent press with limited regional service coverage is a liability in a production environment. The ongoing cost of downtime should be explicitly modeled.
What is your volume-to-capacity utilization target? Equipment ROI is acutely sensitive to utilization rates. A press that breaks even at 70 percent utilization generates strong returns at 85 percent and destroys value at 50 percent. Honest assessment of achievable utilization — based on existing customer demand and realistic new business projections — is essential.
The Honest Conclusion
Eurasian print and textile technology has made genuine, measurable contributions to the profitability of specific segments of the US print industry. It has also consumed capital that some operations could not afford to lose, in pursuit of market positions that the underlying business model could not support.
The difference between those two outcomes is rarely about the equipment. It is about the clarity of strategic thinking that preceded the purchase decision — and the rigor with which the investment was evaluated against the actual competitive and operational realities of a specific shop in a specific market.
The best technology in the world, sourced from the most innovative manufacturers Europe or Asia has to offer, is only as valuable as the business context it operates within.